Enterprise Research & White Paper
Sync Wallet Architecture & Banking Partner Strategy
A comprehensive technical breakdown of Sync Wallet's non-custodial biometric key security, universal PayWithSync multi-rail checkout, and Tier-1 commercial sponsor banking infrastructure.
Official Asset Downloads
Download executive Word documents, raw Markdown, and high-resolution architecture diagrams.
Executive Whitepaper (.docx)
Complete formatted enterprise document with tables, partner matrix, and legal disclosures.
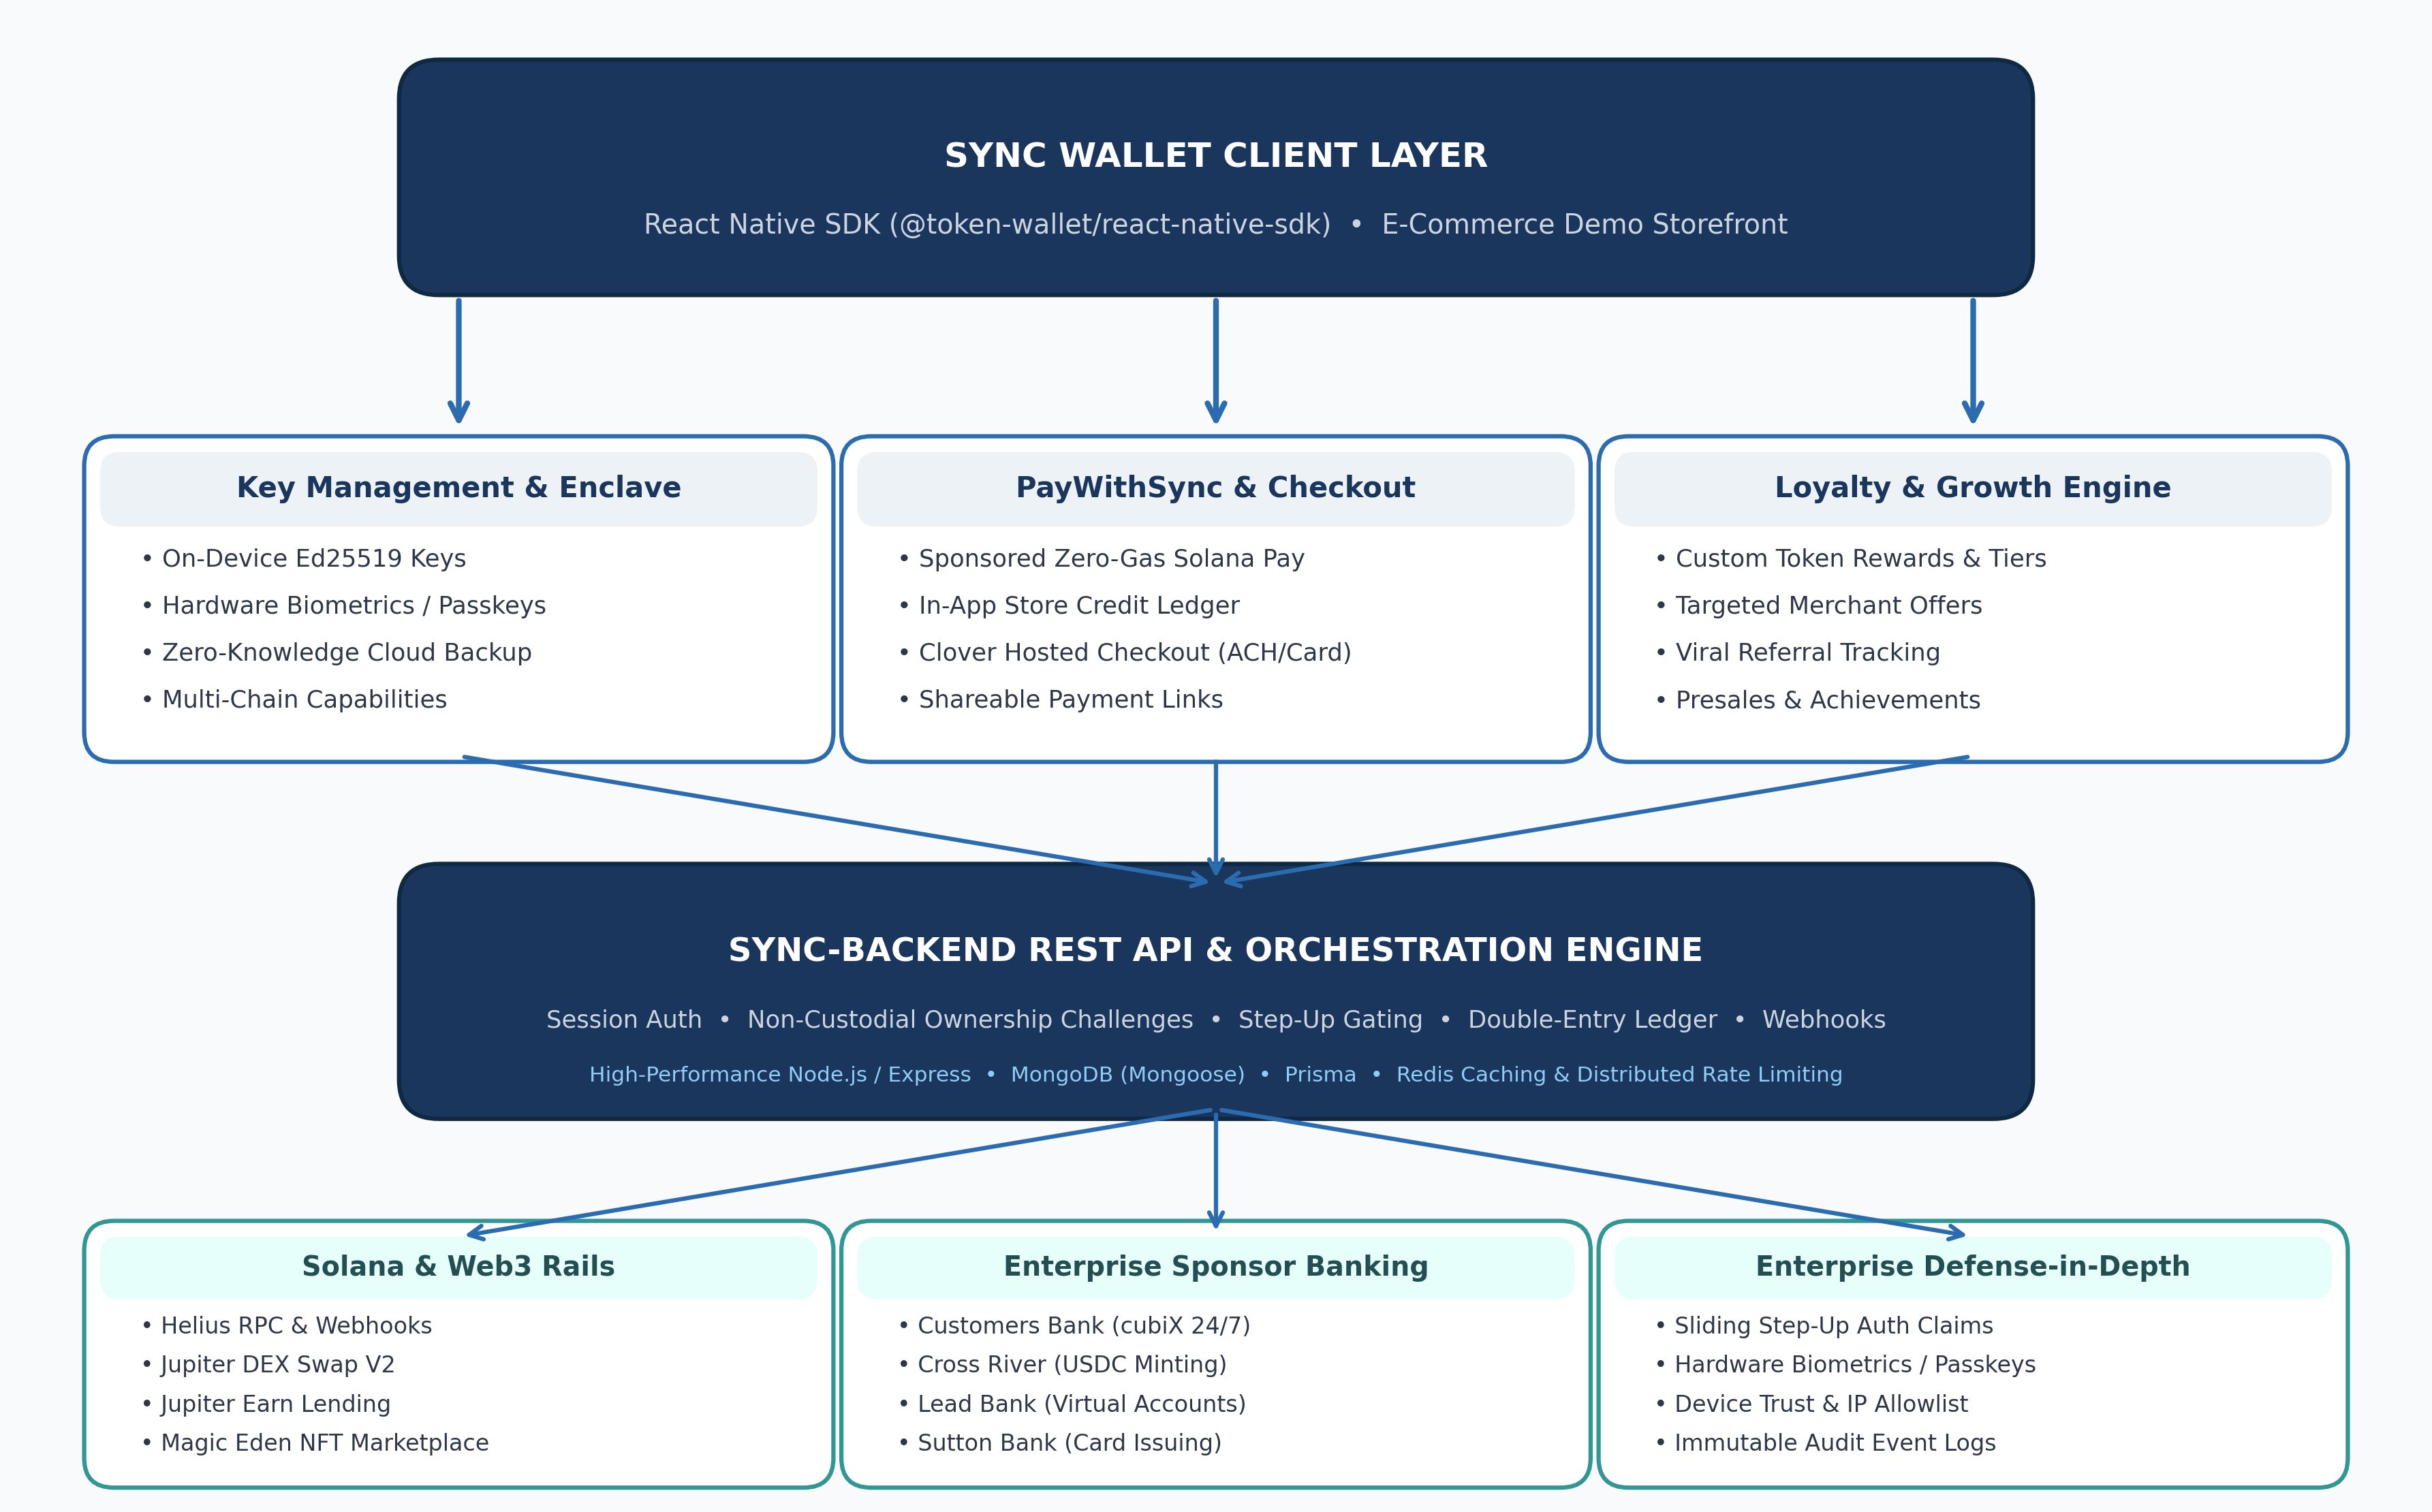
High-Res Architecture Diagram (.png)
300 DPI multi-tier system architecture graphic covering SDK, Backend, and Sponsor Bank layers.
Raw Technical Markdown (.md)
Full version-controlled Markdown source for developers, technical architects, and analysts.
1. Executive Summary
Sync Wallet is an enterprise-grade, non-custodial Web3 & fiat financial platform designed for high-throughput mobile, commerce, and consumer fintech applications. Built primarily around the high-speed Solana blockchain with multi-chain extensibility (EVM, Bitcoin, Hedera, XRP), Sync combines hardware-backed biometric key security, universal merchant checkout (PayWithSync), token presales, loyalty/rewards engines, and multi-rail payment processing.
Core Enterprise Thesis
To elevate Sync Wallet into a true full-stack neobank—capable of offering FDIC-insured stored-value user deposit accounts, wholesale ACH, 24/7 instant FedNow/RTP clearing, branded debit cards, and frictionless crypto on/off-ramps—Sync bridges non-custodial user control with Tier-1 commercial sponsor banking partners.
2. The 5 Core Problems Sync Wallet Solves
Legacy payment rails and first-generation crypto wallets suffer from severe friction: high interchange fees, chargeback vulnerabilities, intimidating seed-phrase UX, and siloed banking connections.
| # | Market Friction | Traditional Problem | How Sync Wallet Solves It |
|---|---|---|---|
| 01 | The Web3 "Usability Wall" | Seed phrases, complex browser extensions, user-funded gas fees, and high onboarding drop-off. | Instant biometric onboarding (FaceID / Passkeys), sponsored gasless Solana transactions, and zero-knowledge client-encrypted cloud backup envelopes. |
| 02 | Excessive Merchant Processing Fees | Credit card interchange fees (2.5%–4.0% + $0.30), friendly fraud / chargebacks, and 2–3 day payout delays. | PayWithSync slashes merchant processing overhead by up to 80%, settles in sub-2 seconds via Solana USDC, and eliminates chargeback risk completely. |
| 03 | Fragmented Banking & Crypto Silos | Users jump between traditional banks, centralized exchanges, and standalone wallet apps. | Unified multi-rail checkout (Solana USDC/SOL, Store Credits, and Card/ACH) with individual FDIC pass-through virtual deposit accounts. |
| 04 | Lack of Built-in Customer Loyalty | Traditional wallets are passive storage tools with zero customer engagement or retention features. | Native tokenized reward programs, customizable VIP tiers (Bronze, Silver, Gold, Platinum), targeted promotional discounts, and viral referral links. |
| 05 | The Security vs. Convenience Dilemma | Exchange collapses / counterparty risk vs. catastrophic loss of unbacked seed phrases. | 100% non-custodial private key sovereignty in device hardware enclaves paired with Step-Up authorization claims and 2FA TOTP. |
3. Key Management & Biometric Enclave
Sync eliminates seed phrases by storing raw cryptographic keypairs directly within device hardware security enclaves (Apple Secure Enclave on iOS, Android KeyStore / StrongBox).
Non-Custodial Architecture
• Hardware Enclave Storage: Keys are generated and retained exclusively on-device.
• Zero-Knowledge Cloud Backup: Cloud backups are encrypted client-side via AES-GCM using user biometric entropy before transmission.
• Step-Up Authorization: Sensitive actions (outbound transfers, refund approvals) require fresh biometric or Passkey verification.
4. PayWithSync & Processing Economics
Through the PayWithSync widget, merchants accept direct payments in digital dollars (USDC on Solana) that settle in under two seconds for fractions of a cent, cutting payment processing overhead by up to 80%.
| Metric | Traditional Credit Cards | PayWithSync (Solana USDC) | Commercial Advantage |
|---|---|---|---|
| Processing Fee | 2.5% – 4.0% + $0.30 per swipe | < 1.0% flat (or sub-penny on Solana USDC) | Up to 80% merchant cost reduction |
| Settlement Speed | 2 to 3 business days (longer on weekends/holidays) | Sub-2 seconds (24/7/365 instant blockchain finality) | Immediate working capital availability |
| Chargeback Risk | High (friendly fraud, dispute fees of $15–$50) | Zero (cryptographically verified irreversible transactions) | Eliminates dispute losses and fraud overhead |
| Onboarding Friction | Manual 16-digit card typing, CVV, billing address | 1-click biometric FaceID / TouchID / Passkey authorization | Higher conversion and lower cart abandonment |
5. Loyalty, Gamification & Growth Engine
Sync transforms passive payments into a customer retention engine with branded token rewards, dynamic VIP tiers (Bronze, Silver, Gold, Platinum), promotional merchant offer claims, and viral referral tracking.
6. System Architecture & 6 Layers
Sync’s multi-tier architecture spans the embeddable client SDK, secure enclave key management, backend orchestration, Solana high-speed consensus, and commercial sponsor banking partners.
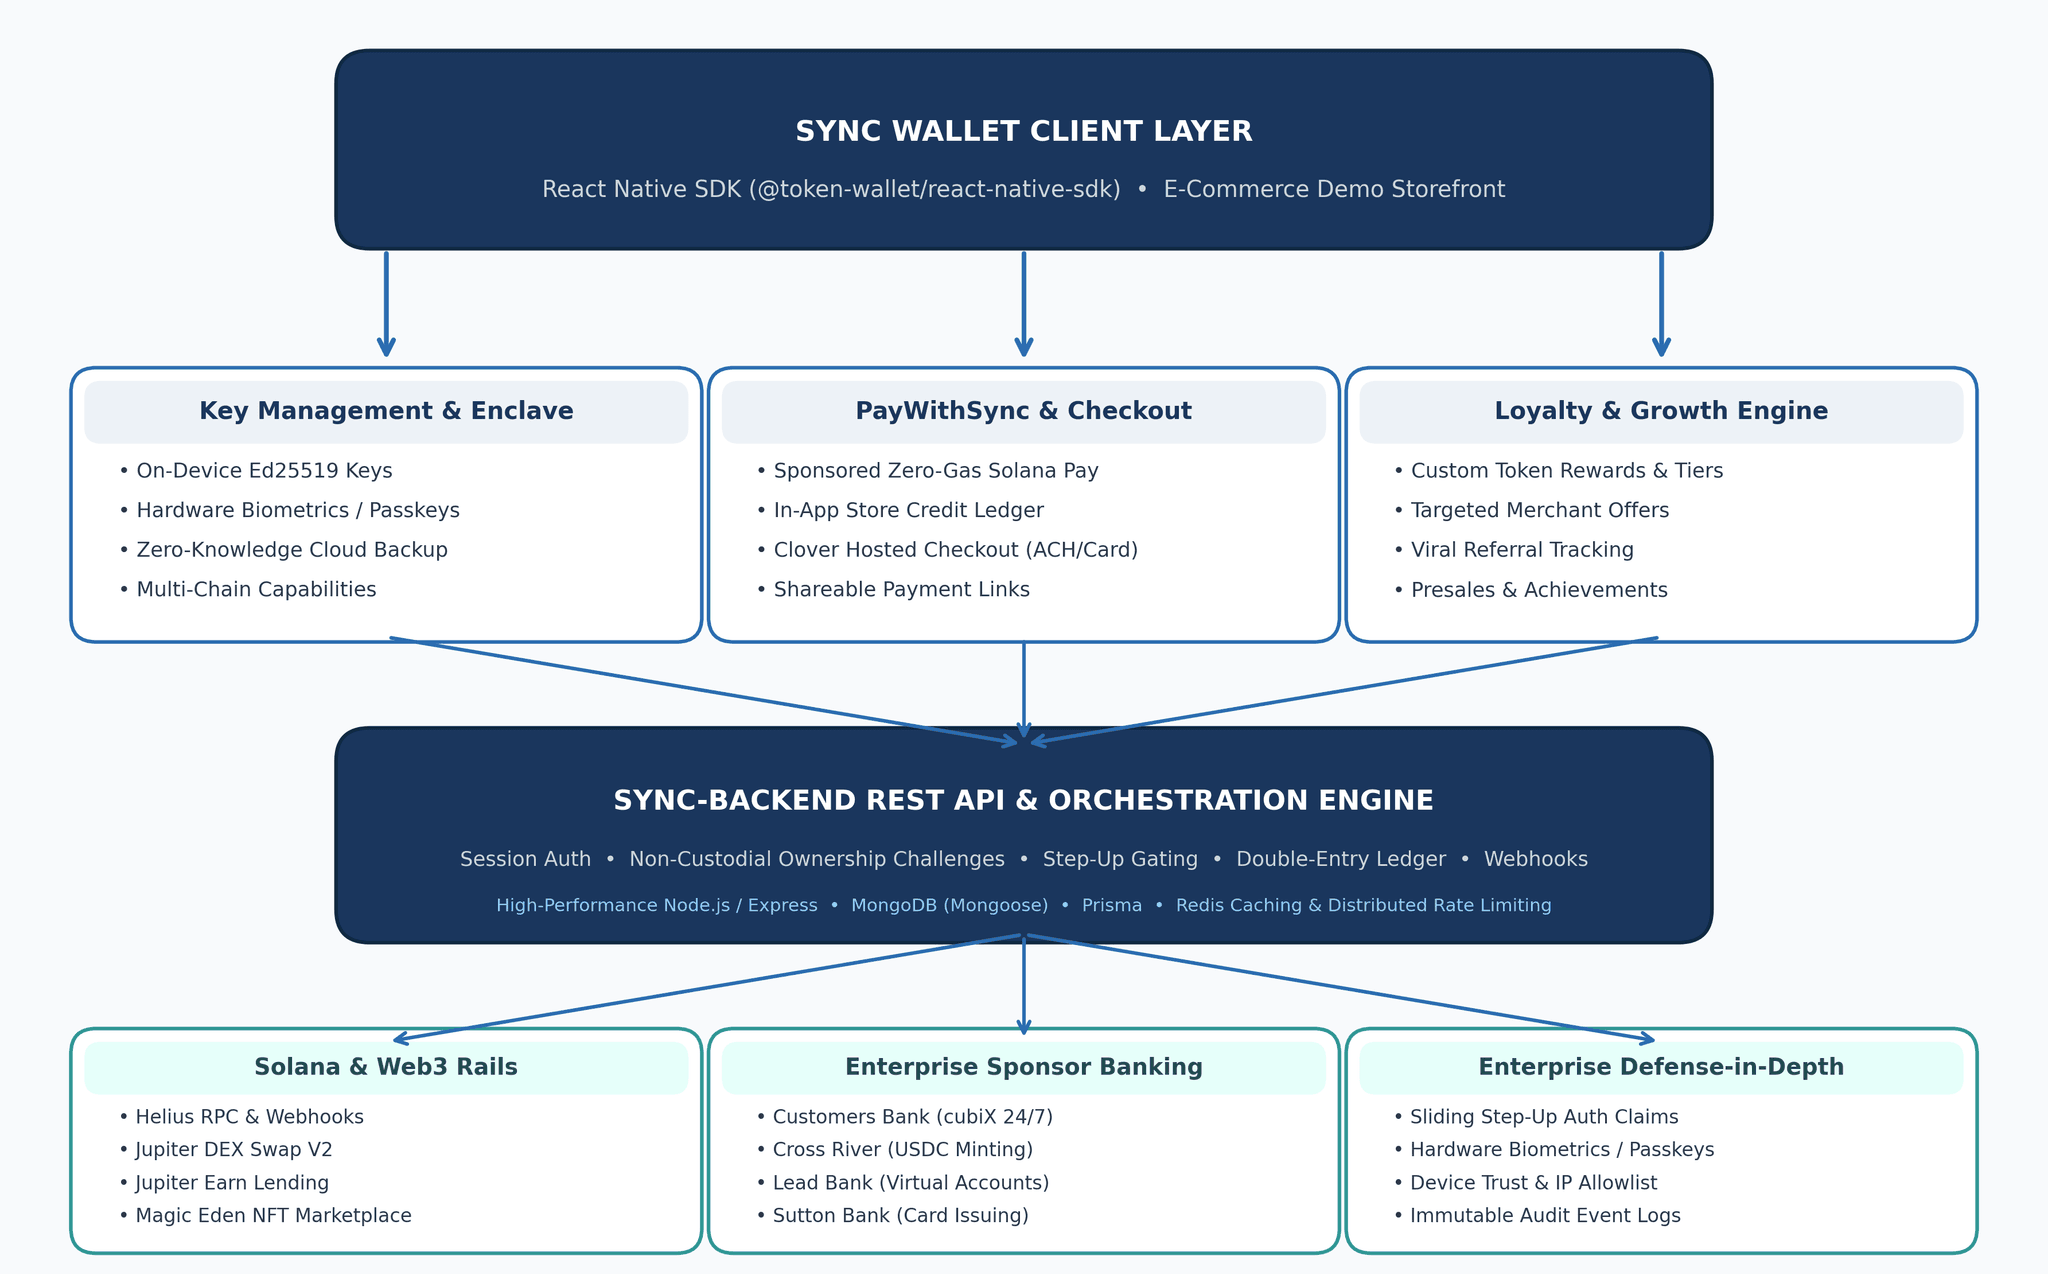
Figure 1: Full-stack system architecture across client SDK, backend services, and sponsor banking rails.
Embeddable mobile UI components, biometric hooks, Solana wallet adapter, and PayWithSync checkout drawer.
Ed25519 keypair generated and secured on-device. Zero-knowledge encrypted backup envelope stored in user cloud.
Instant settlement across Solana USDC, SOL, SPL loyalty tokens, in-app store credits, and Clover/CLIQ card rails.
Custom merchant tokens, tiered VIP rewards, milestone quest achievements, and viral referral conversion tracking.
Sponsored transaction fee payer, fiat banking bridge, webhook verification, idempotent ledger updates, and event analytics.
Solana high-throughput blockchain layer paired with Tier-1 commercial sponsor banks for ACH, FedNow/RTP, and cards.
7. Commercial Sponsor Banking & Neobank Matrix
To provide users with virtual deposit accounts, wholesale ACH, and instant FedNow/RTP clearing, Sync implements a normalised FiatBankingService interface evaluated across leading institutions:
| Institution | Institutional Profile | Key Strengths & Capabilities | Strategic Fit |
|---|---|---|---|
| Customers Bank | Large Regional Commercial Bank ($22B+ Assets) | Dedicated Digital Asset & FinTech banking team, direct FedNow & RTP clearing, low wholesale ACH costs, robust API. | Primary Tier-1 commercial sponsor bank for enterprise scale and institutional credibility. |
| Cross River Bank | Fintech & BaaS Commercial Bank | Pioneer in crypto on/off-ramps, integrated card issuance, virtual account issuance, direct core APIs. | Full-stack partner combining crypto-friendly compliance with card acquiring and issuance. |
| Lead Bank | Venture & FinTech Focused Bank | Modern API infrastructure, strong crypto/Web3 support, flexible virtual account creation and instant payment rails. | High-agility partner for rapid deployment of developer-first banking features. |
| Sutton Bank / Pathward | Premier Card Issuing Institutions | Dominant market leaders in custom branded Visa/Mastercard debit and prepaid card programs. | Ideal partners for physical and virtual consumer debit card rollout. |
| Grasshopper Bank / FV Bank | Digital Commercial Neobanks | API-native architecture, built-in digital asset custody options, frictionless startup onboarding. | Rapid pilot deployment and cross-border settlement flexibility. |
8. Security & Custody Boundaries
Sync maintains a rigorous separation between non-custodial cryptographic key control and regulated banking operations. User private keys never touch Sync servers, while fiat balances and debit card issuance are handled through licensed, FDIC-insured commercial sponsor banks.
Review the technical specifications with our team
Talk to our engineers and partner team about SDK integration, pilot scoping, and sponsor bank onboarding.